Most people learn to invest in the share market with one simple idea in mind: buy low, sell high. Short selling flips this logic on its head. Instead of profiting when a stock price rises, a trader who short sells aims to profit when the price falls.
Short selling in share market is a legitimate and SEBI-regulated trading strategy in India, but it is also one of the most misunderstood. Because it involves selling shares you do not currently own, it carries a different risk profile compared to conventional investing.
Understanding what is short selling, how it works, what it costs, and what can go wrong is essential before anyone considers using it.
This article explains short selling in share market in simple terms, walks through a practical example, covers how it works in India under SEBI's framework, and outlines the risks every trader should know.
What Is Short Selling?
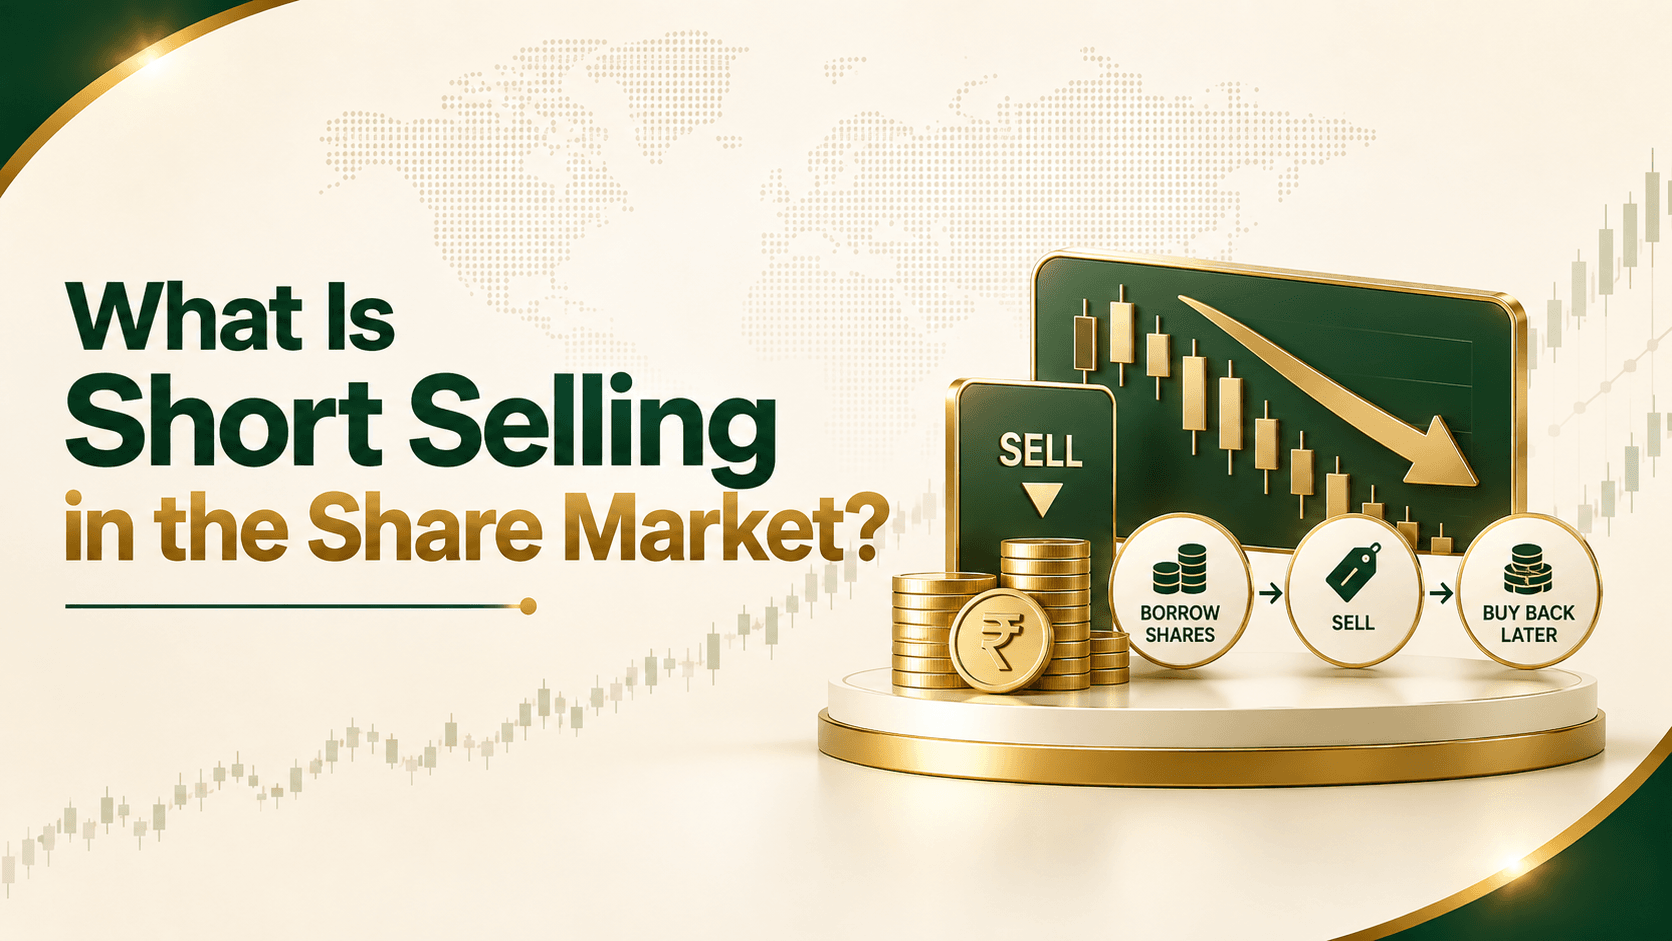
Short selling is the sale of a stock that the seller does not own at the time of the trade. The trader borrows the shares - typically through a broker using the exchange-run Securities Lending and Borrowing (SLB) mechanism - sells them in the open market at the current price, and plans to buy them back later at a lower price to return to the lender.
The difference between the price at which the shares were sold and the price at which they are later repurchased (minus costs) becomes the trader's profit or loss. If the share price falls as expected, the short seller profits. If the price rises instead, the short seller incurs a loss.
The given strategy is commonly used by traders who believe a company is overvalued, is facing weakening fundamentals, or is likely to see negative news flow.
How Does Short Selling Work?
Short selling generally follows this sequence:
- Borrowing the shares: The trader borrows shares from another investor or institution, usually facilitated through the broker or a Securities Lending and Borrowing (SLB) mechanism.
Note: In India, this borrowing typically happens on the exchange’s SLB platform, where lenders and borrowers place orders, and the clearing corporation guarantees settlement.
Selling the borrowed shares: The trader sells these shares in the market at the prevailing price.
Waiting for the price to move: The trader monitors the stock, expecting the price to fall.
- Buying back the shares (covering): The trader repurchases the same number of shares from the open market, ideally at a lower price.
- Returning the shares: The repurchased shares are returned to the lender on the agreed reverse-leg settlement date, closing out the short position.
Throughout this cycle, the trader must also account for borrowing costs, brokerage, and margin requirements, all of which affect the final outcome.
Example of Short Selling
Consider a simplified example to illustrate how short selling works:
Suppose a trader believes shares of Company X, currently trading at ₹500, are overvalued and likely to fall. The trader borrows 100 shares and sells them at ₹500 each, receiving ₹50,000.
A week later, if the share price drops to ₹450, the trader buys back 100 shares for ₹45,000 and returns them to the lender. The trader's gross profit is ₹5,000 (₹50,000 − ₹45,000), before accounting for brokerage, borrowing charges, and taxes.
However, if the share price instead rises to ₹550, the trader would need to spend ₹55,000 to buy back the same 100 shares, a loss of ₹5,000.
In this example, if the position is carried overnight, the shares must be borrowed via the SLB mechanism; intraday shorting in the cash segment does not require SLB.
This example highlights the core principle: profit or loss in short selling depends entirely on price movement after the trade, and losses can occur if the market moves against the position.
Short Selling in India: How Does It Work?
Short selling in share market is legal in India and is regulated by the Securities and Exchange Board of India (SEBI). SEBI introduced a formal framework for short selling to bring transparency and reduce settlement risk.
Key features of this framework include:
Eligibility: Both retail and institutional investors are permitted to short sell.
Eligible stocks: While SEBI’s framework prohibits naked short selling for all securities, in practice, short selling in the cash segment is generally permitted only in stocks that are part of the Futures & Options (F&O) segment. Exchanges and brokers enforce this restriction, and SEBI/stock exchanges periodically review the list.
Naked short selling is banned: All investors must be able to deliver the shares at settlement, meaning short sales must be backed by either owning, borrowing, or otherwise arranging the securities.
Disclosure requirements: Institutional investors must disclose at the time of placing the order whether it is a short sale. Retail investors can make this disclosure by the end of the trading day.
- Institutional restrictions: Institutional investors must settle short sales on a gross basis and typically use the Securities Lending and Borrowing (SLB) mechanism to borrow shares and carry short positions. They are not permitted to square off short positions intraday in the same manner as retail traders in the cash segment.
Reporting: Brokers report scrip-wise short sale and SLB data to stock exchanges as per SEBI/exchange guidelines, enabling monitoring of short interest.
Retail investors typically execute short selling intraday in the cash segment (selling and buying back within the same trading day) because carrying a short position overnight in the cash market requires borrowing shares through the SLB mechanism. This is a key structural difference from markets like the US, where overnight short selling in the cash segment is more commonplace.
It is worth noting that SEBI reviews and refines this framework from time to time, including recent discussions around strengthening the SLB mechanism to make short selling more accessible and efficient. Investors should always check the latest SEBI circulars or consult their broker for the current rules before short selling.
What Is the Difference Between Short Selling and Shorting Futures?
Both strategies allow a trader to profit from a falling price, but they work differently:
Aspect | Short Selling (Cash Market) | Shorting Futures |
What is sold | Borrowed shares of the company | A futures contract on the stock or index |
Ownership | No shares are owned; they are borrowed | No underlying shares are involved directly |
Duration | Typically intraday in the cash segment (SLB needed for overnight) | Can be held until contract expiry |
Margin | Margin plus borrowing cost via SLB | Margin-based, marked-to-market daily |
Settlement | Physical delivery obligation | Cash or physical settlement as per contract and SEBI/exchange norms (many stock futures are physically settled at expiry). |
In practice, many Indian traders who want to hold a bearish position for more than a day prefer shorting index or stock futures, since it avoids the operational complexity of borrowing shares through SLB. This is one reason short selling and futures trading are often discussed together, even though they are distinct instruments.
What Is Short Covering?
Short covering refers to the act of buying back the borrowed shares to close out a short position. Every short sale must eventually be "covered", either voluntarily, when the trader decides to book profit or cut a loss, or involuntarily, if a broker issues a margin call or the position must be squared off due to regulatory or settlement requirements.
In the SLB mechanism, short covering corresponds to the ‘reverse leg’ where the borrower returns the securities on the specified settlement date.
Short covering can sometimes trigger a rapid rise in a stock's price. If many traders are short a stock and the price unexpectedly rises, they may rush to buy back shares to limit their losses. This wave of buying can push the price up further, a phenomenon commonly referred to as a "short squeeze."
What Are the Risks of Short Selling?
Short selling carries a distinct risk profile compared to conventional buying of shares, and investors should understand these risks in detail before considering the strategy:
- Unlimited loss potential: When you buy a share, the maximum you can lose is the amount invested, because a share price cannot fall below zero. In short selling, there is theoretically no upper limit to how high a share price can rise, meaning potential losses are not capped.
- Margin calls: Short positions require margin, and if the stock price moves against the trader, the broker may issue a margin call requiring additional funds or an immediate square-off.
- Short squeezes: A sudden rally, often driven by positive news or heavy buying, can force short sellers to cover at a loss, accelerating the price rise.
- Borrowing costs: Fees for borrowing shares through the SLB mechanism can add up, especially if the position is held for an extended period.
- Timing risk: Even if the underlying view is correct, poor timing can result in losses, since short-term price movements can be volatile and unpredictable.
- Regulatory risk: SEBI has, in the past, imposed temporary restrictions on short selling during periods of extreme volatility, and has clarified that the core framework remains unchanged unless formally notified.
Given these risks, short selling is generally considered more suitable for experienced traders who understand margin trading, technical analysis, and risk management, rather than first-time investors.
Is Short Selling Riskier Than Buying Shares?
In most cases, yes. When buying shares (a long position), the maximum possible loss is limited to the capital invested, since a stock price has a floor of zero. Short selling, on the other hand, has no defined ceiling on potential loss, because there is no upper limit to how much a share price can theoretically rise.
Additionally, short selling requires ongoing margin maintenance, and losses can accumulate faster if the market moves sharply against the position. For these reasons, it is generally regarded as a higher-risk strategy suited to those with experience, discipline, and strict risk management practices, such as stop-loss orders.
Short Selling vs Long Position
Aspect | Long Position (Buying) | Short Selling |
Market view | Bullish - expects price to rise | Bearish - expects price to fall |
Ownership | Shares are owned by the investor | Shares are borrowed, not owned |
Maximum loss | Limited to the amount invested | Theoretically unlimited |
Maximum profit | Theoretically unlimited (as price can rise indefinitely) | Limited to the amount received at sale (as price can only fall to zero) |
Holding period | Can be held for years | Generally short-term; overnight shorting needs SLB |
A long position is the foundation of most share market investment strategies, particularly for those building wealth over the long term. Short selling, by contrast, is typically used for shorter-term, tactical trades.
Short Selling vs Intraday Trading
Short selling and intraday trading are related but not identical. Intraday trading refers to buying and selling a stock within the same trading session, regardless of direction. A trader can go long intraday (buy first, sell later the same day) or go short intraday (sell first, buy back later the same day).
Short selling by retail investors in India is often executed intraday in the cash segment, because carrying a short position overnight in cash generally requires borrowing shares through the SLB mechanism. So while all intraday short trades are a form of short selling, not all short selling is necessarily intraday; some traders use the futures market or SLB specifically to hold bearish positions for longer periods.
Can You Short Sell for More Than One Day?
Yes, but it requires the shares to be properly borrowed. In the cash segment, retail investors who want to carry a short position beyond the same trading day must use the Securities Lending and Borrowing (SLB) mechanism to arrange the shares, since naked short selling, selling without owning or borrowing the shares, is not permitted under SEBI's rules.
Alternatively, many traders who want a multi-day bearish exposure choose to short a futures contract instead, since futures do not require share borrowing and can be held until expiry, subject to daily mark-to-market margin requirements.
SLB tenures typically range from a few days up to 12 months, with specified reverse-leg settlement dates (e.g., first Tuesday of a month), as per exchange SLB rules.
Costs Involved in Short Selling
Short selling is not free, and the associated costs can reduce net profit or add to a loss. Common costs include:
- Brokerage fees: Charged on both the sell and buy-back legs of the trade.
- Securities Transaction Tax (STT) and other statutory levies (including exchange transaction charges, GST on brokerage, and stamp duty) applicable to equity trades.”
- Borrowing/lending fees: If shares are borrowed via SLB, a lending fee is typically charged, which can vary based on demand for that stock.
- Margin requirements: Funds must be set aside as margin, which has an opportunity cost.
- Interest costs: If margin is funded through a loan or leverage facility, interest charges may apply.
Traders should factor in all these costs before assuming a short position will be profitable, since a small price decline may not be enough to offset the cumulative costs involved.
Common Misconceptions About Short Selling
"Short selling is illegal."
This is incorrect. Short selling is legal and SEBI-regulated in India; only naked short selling is banned.
"Short selling always harms the market."
In reality, short selling can contribute to price discovery and add liquidity, as it reflects the views of investors who believe a stock is overvalued.
"Anyone can short any stock."
In India, while SEBI’s framework applies to all listed securities, in practice short selling in the cash segment is generally allowed only in stocks that are part of the F&O segment, as enforced by exchanges and brokers.
"Short selling guarantees profit in a falling market."
Timing, costs, and volatility mean profits are never guaranteed, and losses can occur even in a broadly falling market.
"Retail investors cannot short sell."
Both retail and institutional investors are permitted to short sell under SEBI's framework, though the mechanics differ slightly for each category.
What Happens If the Share Price Keeps Rising?
This is the central risk of short selling. If the share price continues to rise after a short position is opened, the trader's loss increases proportionally, and because there is no ceiling on how high a stock price can go, the potential loss is not capped.
As the price rises, the trader's broker may issue margin calls, requiring additional funds to maintain the position. If the trader cannot meet these calls, the broker may forcibly square off the position, locking in the loss. In extreme cases, if many short sellers rush to cover positions simultaneously, it can trigger a short squeeze, pushing the price up even faster and amplifying losses across the market. This is why disciplined risk management, such as predefined stop-loss levels, is considered essential for anyone considering short selling.
Conclusion
Short selling is a legitimate strategy that allows traders to potentially profit from falling prices, but it comes with a materially different and generally higher risk profile compared to traditional buying of shares. Understanding the mechanics, the SEBI regulatory framework, the associated costs, and above all, the unlimited loss potential, is essential before using this strategy.
Whether you are exploring share market investment for the first time or are an experienced trader evaluating advanced strategies, it is advisable to build a strong understanding of market fundamentals and risk management practices, and to consult a qualified financial advisor or your broker before undertaking short selling.