Introduction: This Dussehra, Which Money Habits Are You Ready to Burn?
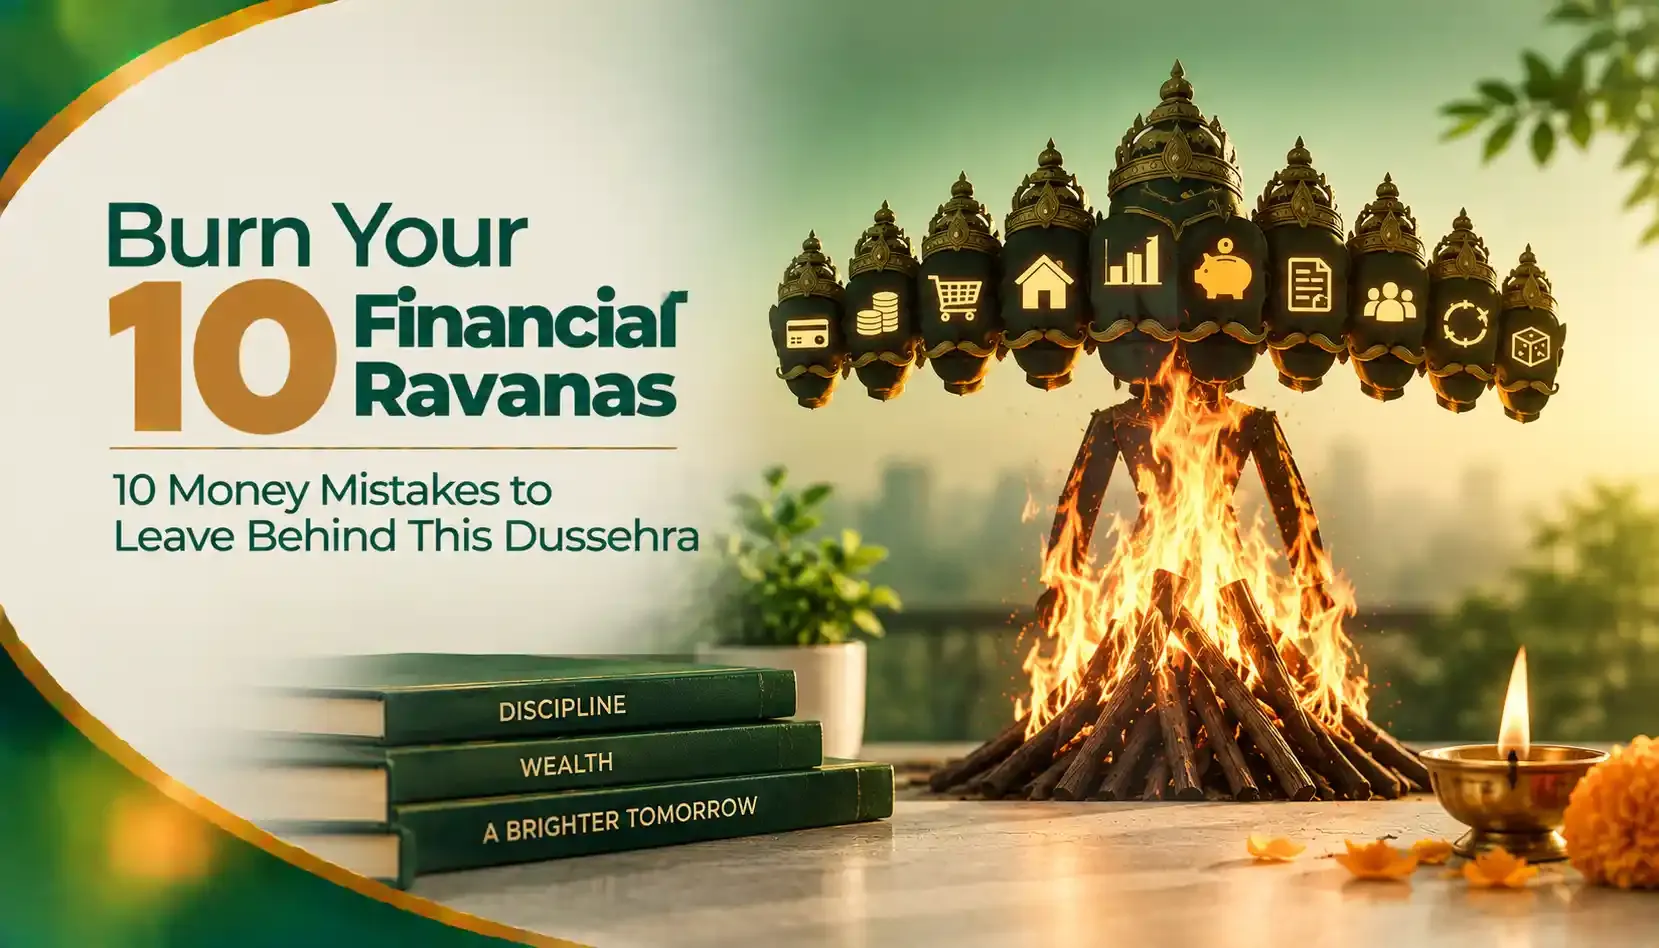
Dussehra celebrates the victory of good over evil. But what if this year, the ten heads of Ravana remind you of something closer to home: the financial habits that could be holding you back?
From chasing tempting opportunities to ignoring sound advice, some of Ravana’s traits offer interesting parallels to the money mistakes people make today.
So, this Dussehra, let’s identify those 10 financial Ravanas and the lessons they can teach us when making money decisions in 2026.
The 10 Financial Ravanas You Should Leave Behind
1. The Ravana of Overspending — Spending Without a Budget
Ever reached the end of the month wondering where your salary went? Maybe unplanned purchases, frequent food deliveries, and lifestyle expenses just added up faster than expected.
Honestly, without a budget, it becomes difficult to understand how much you spend, save, or have available for your financial goals.
How to burn this Ravana: Track your income and expenses, separate essential spending from luxury spends, and set realistic monthly limits. Review your spending regularly to identify areas where you can save without compromising essential needs.
2. The Ravana of Debt — Letting High-Interest Debt Pile Up
Borrowing is not necessarily a financial mistake. However, repeatedly carrying high-interest credit-card balances or taking on loans without assessing repayment capacity can put pressure on your monthly finances.
Interest costs can reduce the money available for savings, investments, and other priorities.
How to burn this Ravana: List your outstanding debts, interest rates, and repayment obligations. Prioritise expensive debt while meeting the required payments on other loans. Before taking on additional debt, assess whether the repayments fit comfortably within your budget.
3. The Ravana of Unpreparedness — Having No Emergency Fund
An unexpected medical expense, a job loss, or an urgent home repair can disrupt even a well-planned budget.
Without readily accessible savings, you may have to borrow money or sell investments at an unfavourable time to cover an immediate expense.
How to burn this Ravana in 2026: Start building an emergency fund based on your essential monthly expenses, income stability, dependents, and existing financial commitments.
4. The Ravana of Delay — Postponing Investments
Waiting indefinitely before making financial decisions may affect how long an investment remains exposed to market movements. For long-term investments, starting earlier can provide sufficient time for potential compounding.
However, investing early does not eliminate market risk, and returns are never guaranteed.
How to burn this Ravana: Define your financial goals, understand your risk tolerance, and explore suitable investment options for your time horizon.
5. The Ravana of Imitation — Following Hype Instead of Research
A stock trending on social media or an investment recommended by a friend can seem difficult to ignore. But popularity alone does not establish whether an investment suits your financial needs.
Remember, “An investment that works for someone else may not be suitable for you.”
How to burn this Ravana: Before investing, research the investment option, understand its risks and costs, and verify information through credible sources to avoid any investment mistake.
6. The Ravana of Greed — Chasing Quick or Guaranteed Returns
In investing, the promise of a quick gain should never replace proper due diligence.
Promises of unusually high returns in a short period can make an opportunity appear irresistible. However, such claims can also be warning signs of investment fraud.
According to SEBI, investors should be cautious about unrealistic return promises, pressure tactics, unsolicited offers, and schemes lacking transparency.
How to burn this Ravana: Question claims of guaranteed high returns, investigate the product and its provider, and never rush into an investment because someone insists that an opportunity will disappear. Understand the risks before committing your money.
7. The Ravana of Concentration — Putting Too Much Money in One Place
What happens if most of your investments depend on one company, sector, or asset class? If that exposure performs poorly, it could significantly affect your overall portfolio.
Owning several investments does not automatically mean your portfolio is diversified. They may carry similar underlying risks.
How to burn this Ravana: Review your portfolio's overall asset exposure, see overlapping holdings (if any), and check the concentration in particular sectors or asset classes.
Because "Diversification can help manage concentration risk, although it cannot eliminate market losses."
8. The Ravana of Neglect — Ignoring Insurance Needs
Building savings and investments is important, but protecting your financial position matters too. Inadequate insurance coverage, where protection is needed, can leave you or your family exposed to substantial expenses or a loss of income.
Insurance needs can change as your circumstances change, so review them periodically.
For example, a household with dependents may need to consider how it would manage financially if its primary earner could no longer provide an income.
How to burn this Ravana: Understand and review your health and life insurance needs in the context of your existing coverage, dependents, liabilities, and financial responsibilities. Also read the policy exclusions, waiting periods, coverage limits, and other applicable terms before purchasing or renewing a policy.
9. The Ravana of Unplanned Goals — Saving Without a Clear Purpose
Saving money is a positive habit, but saving without a defined objective can make it difficult to determine how much you need or when you will need it.
A home purchase, higher education, retirement, and a short-term purchase have different time horizons and financial requirements.
How to burn this Ravana: Define your financial goals, estimate their costs, and set realistic timelines. Match your savings and investment approach to when the money will be required and how much risk you can reasonably take.
10. The Ravana of Complacency — Never Reviewing Your Financial Plan
A financial plan that suited you a few years ago may no longer reflect your current income, expenses, family responsibilities, or goals.
With passing years, ignoring these changes can leave your savings targets outdated and make your portfolio misaligned.
How to burn this Ravana: Review your financial plan periodically and after significant life events, such as a change in income, marriage, parenthood, or a major purchase. Check your progress, reassess your priorities, and make adjustments when necessary.
Conclusion: Let Your Financial Habits Have a Fresh Start
This 2026 Dussehra, burn your financial Ravanas & let go of the money habits that no longer serve you and make room for better financial decisions.
Track your spending, manage debt, prepare for unexpected expenses, research investments, and review your financial goals every year.
Because “The Real Victory isn't about making every financial decision perfectly. It's About Learning From Mistakes, Questioning Assumptions And Making Informed Choices As Your Circumstances Evolve.”