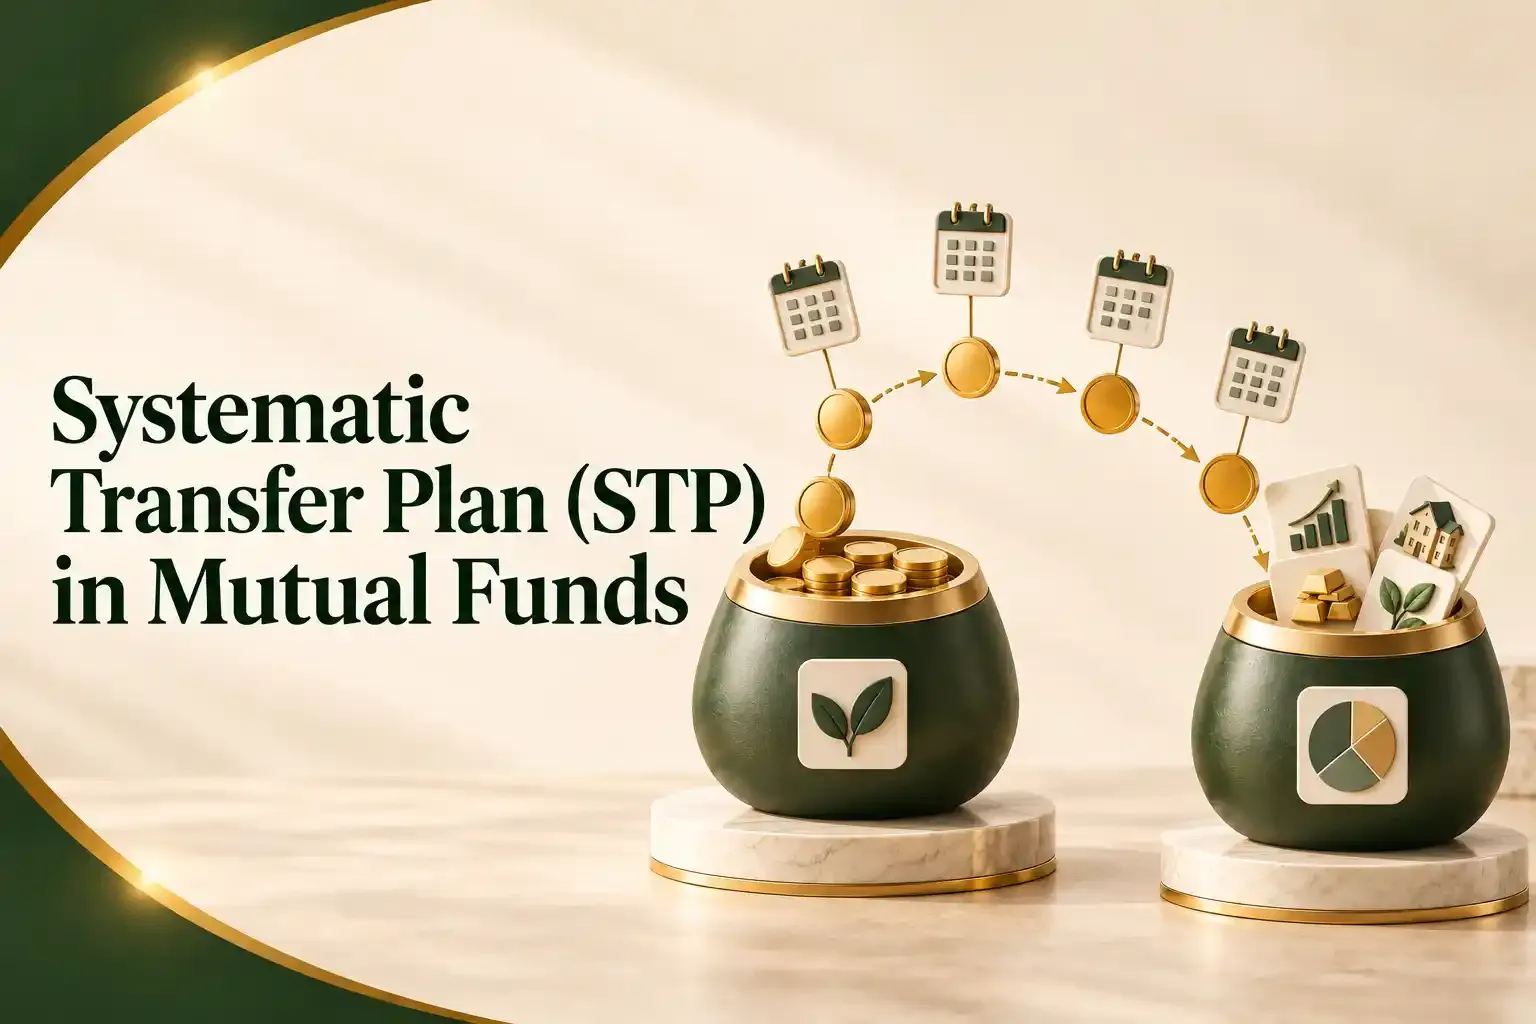
If you have a lump sum to put into equity funds, you may wonder whether to invest it all today or in parts. A systematic transfer plan (STP) is one way to do the latter.
In short: An STP moves a fixed amount at regular intervals from one mutual fund scheme to another scheme of the same fund house, for example, from a liquid fund to an equity fund. Your money enters the market in phases instead of all at once. An STP does not remove market risk or guarantee returns. It helps you manage the timing of your entry.
This guide explains what a systematic transfer plan is, how it works, what it costs, how it is taxed, and what to check before you start.
Quick Takeaways
- An STP transfers money between two schemes of the same AMC on a schedule you choose.
- It is commonly used to invest a lump sum in equity funds gradually.
- The three main types are Fixed, Capital Appreciation, and Flexi STP.
- An STP may reduce the impact of poor entry timing, but it does not remove market risk. It also does not guarantee better returns than a one-time investment.
- Each transfer counts as a redemption from the source scheme, so it can attract tax and exit load.
- SIP adds fresh money from your bank account, STP moves existing mutual fund money, and SWP pays money out to you.
What Is STP in Mutual Funds?
A systematic transfer plan is a facility offered by mutual fund houses. You invest a lump sum in one scheme, called the source scheme. You then instruct the fund house to move a set amount at fixed intervals into another scheme, called the target scheme.
Investors most often use a low-volatility debt or liquid fund as the source and an equity fund as the target. The reverse is also possible, for example, moving gains from an equity fund into a debt fund to protect them.
How Does an STP Work?
Here is how a systematic transfer plan works in practice:
- Invest in the source scheme. You first invest a lump sum in a scheme that offers the STP facility.
- Choose the target scheme. It must be from the same fund house.
- Set the terms. You choose the amount, frequency (commonly weekly, monthly, or quarterly, depending on the AMC), start date, and number of installments.
- Transfers happen automatically. On each date, units worth the chosen amount are redeemed from the source scheme at that day's NAV. The same amount is invested in the target scheme at its NAV.
- The rest stays invested. The balance in the source scheme keeps earning whatever that scheme earns, which is not guaranteed, until the next transfer.
Many investors now register STPs through mutual fund online platforms, usually after completing KYC and holding a folio with the AMC. Processing timelines and minimum amounts vary by AMC, so check the scheme documents.
Example of STP
This is an illustration only. The NAVs are hypothetical and do not represent any scheme or predict returns.
Suppose you invest ₹6,00,000 in a liquid fund and set up a monthly STP of ₹1,00,000 into an equity fund for six months.
| Month | Amount transferred | Hypothetical NAV of target fund | Units allotted |
|---|---|---|---|
| 1 | ₹1,00,000 | ₹100 | 1,000.00 |
| 2 | ₹1,00,000 | ₹95 | 1,052.63 |
| 3 | ₹1,00,000 | ₹90 | 1,111.11 |
| 4 | ₹1,00,000 | ₹98 | 1,020.41 |
| 5 | ₹1,00,000 | ₹105 | 952.38 |
| 6 | ₹1,00,000 | ₹110 | 909.09 |
| Total | ₹6,00,000 | - | 6,045.62 |
Your average cost per unit is about ₹99.25 (₹6,00,000 ÷ 6,045.62). When the NAV fell, the same ₹1,00,000 bought more units. When it rose, it bought fewer.
If the equity market had risen steadily, a one-time investment on day one could have done better. Staggered trades some potential upside for lower timing risk. Which outcome you get depends on how markets behave, and nobody can predict that.
What Are the Types of STP?
Fund houses commonly offer three variants. Names and features can differ, so confirm with the AMC.
- Fixed STP: You transfer a fixed amount at each interval. This is the simplest and most widely used type.
- Capital Appreciation STP: Only the gains earned in the source scheme since the last transfer are moved to the target scheme. Your original investment stays in the source scheme. Because gains vary, the transfer amount is not fixed.
- Flexi STP: The transfer amount changes according to a formula or the investor's specified conditions, within limits set by the AMC. You may specify a minimum amount and a variable component.
Why Do Investors Use STP?
- Phased entry: It suits people who receive a lump sum, such as a bonus, sale proceeds, or maturity amount, and prefer not to invest it all in equity at once.
- Discipline: Transfers run on a schedule, which reduces the urge to time the market or delay.
- Useful parking place: Until it is transferred, the money sits in a scheme that is generally less volatile than equity. Those schemes still carry their own risks and offer no assured returns.
- Gain protection: An STP from equity to debt can help lock in gains gradually as a goal approaches.
For those who want to invest in mutual funds with a lump sum, an STP can be a practical way to build an equity position without deciding on a single entry date.
Does STP Reduce Investment Risk?
Partly, but not completely.
An STP can reduce timing risk, the chance of investing the whole amount just before a market fall. It does not reduce the risk of the target scheme itself. If the equity market declines over the entire transfer period, your investments will show losses.
The source scheme also carries risk. Liquid and short-duration debt funds have historically been less volatile than equity funds, but they are not risk-free. Their returns are not guaranteed and can be affected by interest rate movements and credit quality.
Before starting an STP, read the scheme's riskometer and its Scheme Information Document (SID), and check whether the scheme matches your risk appetite and time horizon.
STP vs SIP vs SWP
| Feature | STP | SIP | SWP |
|---|---|---|---|
| Full form | Systematic Transfer Plan | Systematic Investment Plan | Systematic Withdrawal Plan |
| Money moves | From one scheme to another (same AMC) | From your bank account to a scheme | From a scheme to your bank account |
| Best suited for | Investing a lump sum in phases | Building wealth from regular income | Generating periodic cash flow |
| Requires existing investment? | Yes, in the source scheme | No | Yes |
| Tax event? | Yes, each transfer is a redemption | Only when you redeem | Yes, each withdrawal is a redemption |
What Are the Costs and Tax Implications of STP?
Is STP Taxable?
Yes. An STP is treated as a redemption from the source scheme followed by a fresh purchase in the target scheme. Any gain on the units redeemed in each transfer is taxable in that financial year. Units are redeemed on a first-in, first-out (FIFO) basis.
Under current rules for FY 2026-27, the broad treatment is:
| Source scheme type | Holding period | Tax treatment |
|---|---|---|
| Equity-oriented funds | 12 months or less | Short-term gains taxed at 20% |
| Equity-oriented funds | More than 12 months | Long-term gains above ₹1.25 lakh in a financial year taxed at 12.5% |
| Debt-oriented funds (units bought on or after 1 April 2023) | Any period | Gains taxed at your income tax slab rate |
Surcharge and cess apply on top. Other categories, such as hybrid, gold, international funds and older debt fund units, follow different rules. Check the applicable provisions with a qualified tax professional, since tax laws change.
Does STP Have Any Exit Load?
It can. Exit load depends on the source scheme's terms. If you transfer units out before its exit load period ends, the load may apply. Many liquid funds charge a graded load only in the first few days, while some equity and hybrid schemes charge around 1% if units are redeemed within a year. These terms differ by scheme, so check the SID.
Also note that each STP installment creates a new purchase in the target scheme. The target scheme's exit load period and the 12-month holding period for tax are counted separately from the date of each installment. SEBI's Mutual Funds Regulations, 2026, effective 1 April 2026, place an upper limit on exit loads, and most schemes charge much less than that limit.
Are There Any Other Charges?
- Expense ratio: Both schemes charge an ongoing fee, which is built into the NAV. Under SEBI's 2026 framework, statutory levies are shown separately from the base expense ratio.
- Statutory charges: Securities Transaction Tax may apply on redemption of equity-oriented units, and stamp duty applies on unit purchases, as notified from time to time.
- TDS: For resident individuals, mutual fund capital gains are generally not subject to TDS at the time of redemption, but NRI investors face tax deducted at source.
Most STPs carry no separate fee. Read the offer document to confirm.
What Should You Check Before Starting an STP?
- Goal and time horizon: An STP into equity generally suits goals that are several years away.
- Source and target schemes: Check the category, risk level, exit load, and whether the AMC offers STP between them.
- Minimums: Ask about the minimum investment in the source scheme, the minimum transfer amount, and the minimum number of installments.
- Frequency and tenure: Choose these so that the transfer stretches over a period you are comfortable with.
- Tax impact: Estimate the tax on gains from each transfer, especially if the source scheme is equity-oriented.
- Plan type: Confirm whether transfers are allowed between your source and target plans (Regular or Direct).
- Processing time: Register early, as most AMCs need some working days before the first transfer.
- Balance: Make sure the source scheme has enough units. If the balance is short, the transfer may fail or end early.
Can You Do an STP Between Different Mutual Fund AMCs?
No. An STP works only between schemes of the same mutual fund house. SEBI describes it as a transfer from one scheme of a mutual fund to another scheme of the same mutual fund.
If you want to move money to a different AMC, you would need to redeem units in the first scheme and invest the proceeds in the second. That is a separate transaction, and it may attract exit load and tax. You can then set up a fresh STP or SIP in the new scheme.
In July 2026, SEBI also extended the standing instruction facility for SWP and STP to mutual fund units held in demat form, to be rolled out in phases through April 2027. If you hold units in a demat account, ask your relationship manager what is currently available.
What Happens When an STP Ends?
When the last installment is processed, the plan closes. Here is what remains:
- In the target scheme: All units allotted so far continue to be invested. They remain subject to market movements until you redeem them.
- In the source scheme: Any leftover balance stays invested. Depending on the AMC, the remaining balance may be transferred in the final installment, or it may need to be redeemed or switched separately.
After the STP ends, review your portfolio against your goals. You may choose to continue with a SIP, leave the investment untouched, or rebalance. There is no automatic next step.
Common Misconceptions About STP
"An STP guarantees better returns than a lump sum."
It does not. A lump sum can outperform in a rising market, and an STP can help in a falling or volatile one. The result depends on how markets behave.
"An STP makes my investment safe."
An STP spreads out your entry timing. It does not protect against losses in the target scheme.
"STP transfers aren't taxed."
Every transfer is a redemption and can create a taxable gain.
"STP and SIP are the same."
A SIP invests fresh money from your bank account, while an STP moves money already invested with the fund house.
"I can do an STP to any fund."
The target scheme must belong to the same AMC as the source scheme.
"A longer STP is always better."
There is no ideal duration. A very long STP keeps a large part of your money in the source scheme, which may not match your long-term allocation.