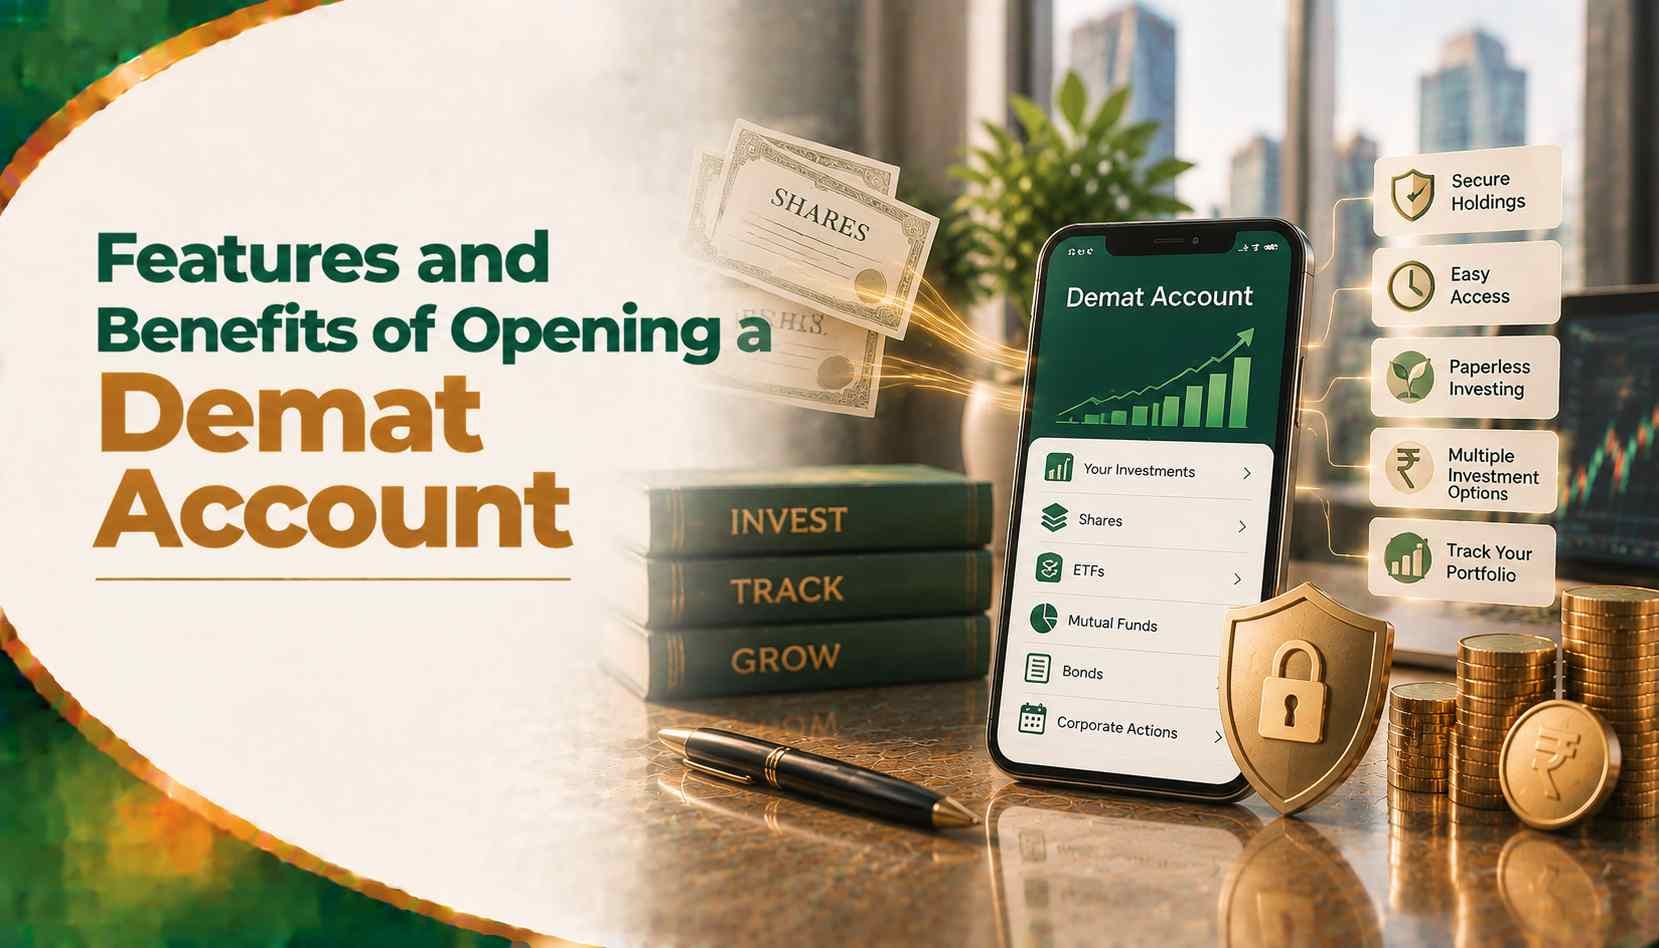
Opening a Demat account is usually the first practical step anyone takes before investing in the Indian stock market. Yet many first-time investors treat it as a formality, a box to tick before they can start buying shares, without understanding what the account actually does, what protections it offers, or how it fits into the broader framework of trading and settlement in India.
This blog is meant to fix that gap. We'll walk through what a Demat account is, its key features, the real benefits it offers investors, and what beginners specifically need to know before opening one.
What Is a Demat Account?
A Demat (Dematerialised) account is an electronic account that holds your shares, bonds, mutual fund units, exchange-traded funds (ETFs), and other securities in digital form, replacing the physical share certificates that were once the norm. It functions much like a bank account, except instead of holding money, it holds securities.
In India, Demat accounts are maintained through two depositories - the National Securities Depository Limited (NSDL) and the Central Depository Services Limited (CDSL) - and are opened via a Depository Participant (DP), typically a stockbroker or bank registered with SEBI.
A Demat account is usually opened alongside a linked trading account, since one holds your securities and the other is used to place buy and sell orders on the stock exchange.
Key Features of a Demat Account
Before deciding to open a Demat account, it helps to understand what it actually offers on a day-to-day basis.
1. Electronic Holding of Securities:
All your shares, bonds, government securities, mutual fund units, and ETFs are held in digital form, eliminating risks associated with physical certificates such as loss, theft, forgery, or damage.
2. Linked Bank and Trading Account:
A Demat account works alongside a trading account and your bank account, forming a three-way link that allows shares to move in and out and funds to settle automatically when you buy or sell.
3. Unique Identification Number:
Every Demat account holder is assigned a unique Beneficial Owner Identification Number (BO ID), which is used to identify and track holdings and transactions.
4. Multiple Types of Securities in One Place:
A single Demat account can hold equities, corporate and government bonds, ETFs, SGBs, and, where purchased through the exchange route, mutual fund units, consolidating many asset classes under one account.
5. Nomination Facility:
Account holders can nominate a beneficiary to receive their holdings in case of an unforeseen event. Under SEBI's revised nomination framework, nomination is mandatory for all new single-holder Demat accounts and mutual fund folios. Investors who do not wish to nominate anyone will need to submit a formal opt-out declaration instead. Joint accounts remain unaffected by this requirement.
6. e-KYC and Paperless Onboarding:
Most Depository Participants now offer a fully digital account-opening process using Aadhaar-based e-KYC, PAN verification, and digital signatures, reducing paperwork and turnaround time significantly.
7. Account Statements and Transaction Tracking:
Holders receive periodic statements detailing their holdings, corporate actions (such as dividends, bonus issues, and stock splits), and transaction history, offering transparency at every stage.
8. SEBI Regulation and Depository Oversight:
Demat accounts operate under SEBI's regulatory framework and are monitored by NSDL and CDSL, which adds a layer of institutional oversight and investor protection.
Benefits of Opening a Demat Account
Understanding the features naturally leads to the more practical question: what are the benefits of a Demat account for an everyday investor?
- Safety and Reduced Paperwork: Since securities are held electronically, there is no risk of physical certificates being lost, stolen, mutilated, or forged, a genuine concern in the pre-dematerialization era.
- Faster and Easier Transactions: Buying and selling securities is executed electronically, with settlement on a T+1 rolling cycle, i.e., funds and securities are settled on the next working day after the trade date.
- Lower Transaction Costs Over Time: Electronic holding removes costs associated with physical transfers (courier, handling, legacy stamping on paper instruments). Stamp duty is still applicable on electronic transactions as per current rules.
- Easy Portfolio Consolidation and Monitoring: Because equities, bonds, mutual funds, and ETFs can all sit in one account, investors get a consolidated, real-time view of their portfolio rather than tracking holdings across multiple certificates or folios.
- Convenient Access to Corporate Actions: Dividends, interest payments, bonus shares, and rights issues are credited automatically to the linked Demat and bank accounts, without the need for manual claims.
- Loan Against Securities: Many banks and NBFCs allow investors to pledge securities held in a Demat account as collateral for loans, offering a way to access liquidity without liquidating investments.
- Transparency and Auditability: Every transaction is recorded and time-stamped by the depository, creating a clear, verifiable trail that benefits both the investor and the regulator.
Demat Account for Beginners: What You Need to Know
If you're opening a Demat account for the first time, a few practical points are worth keeping in mind.
1. Documents required:
PAN card, Aadhaar or another address proof, a cancelled cheque or bank statement, a passport-size photograph, and a signature specimen. Most Depository Participants now accept these digitally during e-KYC.
2. Choosing a Depository Participant:
Look at the DP's SEBI registration status, the depository it operates under (NSDL or CDSL), account maintenance charges (AMC), brokerage structure, and the quality of its trading platform and customer support.
3. Charges:
Demat account opening is usually free or low-cost to initiate, but most DPs charge an annual maintenance fee and transaction-based charges. It's worth reviewing the full fee schedule before signing up, since costs vary meaningfully between providers.
4. Start with your investment goal in mind:
A Demat account is a facility, not a strategy. Before you open one, have a basic sense of whether you're investing for the long term, trading actively, or building a mix of equity and debt instruments; this will influence which broker and account type suit you best.
5. Nomination:
Nomination matters, even where it isn't yet mandatory for your account type. Given SEBI's updated framework, it is good practice to complete your nomination (or a considered opt-out) at the time of account opening rather than treating it as an afterthought.
6. Securities market investments are subject to market risk:
A Demat account only facilitates the holding and settlement of securities; it does not guarantee returns, and the value of your investments can go up or down based on market conditions. Read all scheme- and product-related documents carefully, and consult a SEBI-registered investment advisor if you are unsure about your investment decisions.
Conclusion
A Demat account is now a basic requirement for anyone looking to participate in India's securities market, and for good reason: it replaces a slow, paper-heavy system with one that is faster, safer, and easier to track. But opening one is only the starting point. Understanding its features, staying compliant with regulatory requirements like nomination, and choosing a Depository Participant that fits your needs are what actually determine whether the experience works well for you as an investor.
If you're ready to open a Demat account, it's worth taking the time to compare providers on regulatory standing, transparency of charges, and platform reliability, rather than opening the first account you come across.